
Find answers to common questions about our credit repair services, pricing, policies, and processes.
A hard inquiry (also called a hard pull) is when a lender checks your credit report because you applied for credit.
A collection account is a negative credit item that appears when a bill goes unpaid for a long period and the original creditor sends or sells the debt to a collection agency.
A late payment on a credit report is a negative mark that shows you didn't pay a credit account on time according to the lender's due date.
A student loan is borrowed money used to pay for education that you must repay—with interest—after (and sometimes during) school.
An eviction is a legal process where a landlord forces a tenant to move out of a rental property—usually because the tenant violated the lease or failed to pay rent.
A medical bill is a charge you receive for healthcare services that were provided to you—but not fully paid for by insurance (or not insured at all).
A charge-off account is a debt that a lender has decided is unlikely to be collected, so they mark it as a loss in their accounting—but you still owe the money.
A repossession (often called a repo) happens when a lender takes back property you're financing—most commonly a car—because payments weren't made as agreed.
A bankruptcy is a legal process that gives a person or business relief from overwhelming debt when they can no longer afford to pay what they owe.
A public record on a credit report is a negative legal or financial event that comes from court filings or government records and is reported to the credit bureaus because it involves unpaid obligations or legal responsibility.
ChexSystems is a consumer reporting agency that banks and credit unions use to decide whether to approve or deny you for a checking or savings account—not loans or credit cards. Think of it as a credit report for bank accounts.
Early Warning Services (EWS) is a consumer reporting agency used by banks to decide whether to approve you for checking and savings accounts and to monitor for fraud. It's similar to ChexSystems—but more powerful—and is heavily used by major banks.
Debt consolidation is a financial strategy where you combine multiple debts into one single payment, usually with the goal of lowering your interest rate, reducing your monthly payment, or simplifying your finances.
Chexsystems / Early Warnings (Sold Separately) — $500 Each Individually | $750 For Both Total Combined = $250 OFF
I do not answer random calls or text messages. The majority of commonly asked questions are already addressed in the Education Tab and FAQ Section on my website.
Most calls naturally turn into full consultations. My time and expertise are both valuable. Therefore, I reserve my time for individuals who are serious and prepared to move forward.
My website has all the information you may need. Additionally, you may utilize the Support Chat Box, conveniently located on the bottom right-hand side of the website, for faster responses or further assistance.
Unfortunately I do not answer random calls. Most of your questions are under my FAQ page on my website. If you have general questions that may not be on my website you have 3 options.
Option A. Inbox Me On Facebook
Option B. DM me on Instagram
Option C. Text my support number with your first and last name just so I can know who I’m speaking with.
Feel free to send your questions here. If you feel like the message may be too long to type just send a voice message and I’ll be happy to answer them all. But if I have to stop what I’m doing to answer your questions over the phone, then you will be required to schedule a consultation.
Customer Service Number: 312-584-9969
Customer Service Email: Support@wealthyintention.org
Yours Truly, TheCreditDaddy
If your credit is already good, realistically you don’t need me or anyone else to obtain business funding. You should be able to just apply and get approved, and the process should be a very smooth transaction.
On the flip side, if you are not in a position to confidently request six-figure funding from a financial institution, your credit profile may not be as strong as you believe. Having “good credit” means more than a high score.
For the statement “I have good credit” to be accurate, four key elements must be in place:
Why do you need all four? Because all 4 combined is WHAT MAKES YOU CREDIBLE. And remember — YOUR CREDIT IS YOUR CREDIBILITY.
Even if you had a good credit score, clean and accurate credit report, and a strong profile, you can still be denied business funding if the LLC is not set up PROPERLY. Entity structure, compliance, and financial alignment play a critical role in lender approval.
Your LLC/Business is WHAT GIVES YOU ACCESS to over 150K or more. Not to mention all of the tax benefits associated with being a business owner.
This is a separate — but equally important — conversation. If you would like to determine whether your LLC is properly established, or need assistance with setup and compliance, you are encouraged to schedule a consultation.
Short Answer: Yes, but it’s not as simple as these YouTube and TikTok gurus make it seem.
May I remind you that your CREDIT is your CREDIBILITY. Meaning your financial reputation with banks, credit unions, and lenders. It tells financial institutions how you’ve handled the ability to borrow money and repay it responsibly.
I understand that many people have adopted the mindset that “business credit is completely separate from personal credit.” While there may be some truth to that when it comes to receiving a hard inquiry or reporting utilization on business credit cards to your personal credit report, what people fail to realize is that you establish BUSINESS CREDIT the same way you establish PERSONAL CREDIT — by getting approved for credit and PROVING THAT YOU CAN PAY IT BACK ON TIME.
Whether we’re talking about personal credit or business credit, lenders ultimately want to see the same thing:
That’s why I always say: CREDIT = CREDIBILITY. Think about it: you cannot build a credit history without first establishing a history of borrowing and making on time payments.
The stronger your track record, the more confidence banks and lenders can have in doing business with you. I say that to say this…
Major Lenders Vs Private Lenders
Two popular ways of receiving funding — see the two dropdowns below.
This opportunity is available to business owners who meet the revenue requirements, but it can be especially valuable for individuals who need access to business capital now and do not want to wait until the credit repair process is complete.
I can assist business owners with obtaining business funding based primarily on their monthly revenue and cash flow, if they can provide verifiable business bank statements and tax returns.
To qualify, the business should consistently generate a minimum of $10,000 per month. ALL REVENUE must be deposited into an established BUSINESS BANK ACCOUNT. This means you CANNOT combine personal bank statements with business bank statements to meet that 10K mark.
Having business tax returns can strengthen the application, but they are not necessarily a deal breaker if you do not have them.
This is revenue and cash flow-based funding, meaning the amount you may qualify for is primarily determined by how much revenue your business generates each month and how much money you’re keeping in the bank account at all times.
For example, if your business consistently generates $50,000 per month, you could potentially qualify for funding in the range of approximately $40,000–$50,000+, depending on the lender’s underwriting and other qualifying factors. If your business only generates $10,000 per month, then you may only qualify for about $7,000–$15,000.
Another major benefit is that every halfway mark of the loan term, you may have the opportunity to refinance and apply for additional funding, subject to continued qualification. This means if you take out a 10K loan for example and have 12 months to pay it off. The halfway mark for 12 months would be 6 months. So at the 6 month mark if you have made all payments on time up to that point, you could potentially qualify to refinance the loan for more capital.
Secure an instant pre-approval. Our application process is straightforward and can be completed in seconds.
If you do not already have an established business that’s generating a minimum of 10K per month, then unfortunately this option does not work for you. A major lender would be a much better fit, as business revenue is not a deal breaker.
Some major banks and credit unions include Chase, Navy Federal, Bank of America, Wells Fargo, PNC and many others as the list goes on.
This option is available to newly established business owners and small businesses. It can be especially valuable for individuals with a strong personal credit profile who want access to traditional bank financing. If your goal is to qualify for traditional bank loans, lines of credit, or higher-limit credit products with potentially more favorable rates and terms, building a strong credit profile is extremely important.
When it comes to traditional loans from major lenders there is something very important that every future or current business owner needs to understand:
A BUSINESS LOAN doesn’t automatically mean your personal credit is irrelevant. Simply having a “BUSINESS” does NOT guarantee that your business WILL MAKE MONEY.
Think about it this way: if you take out a $50,000 business loan, but your business isn’t generating enough revenue to comfortably repay that loan, who does the business ultimately have to fall back on?
This is exactly why personal credit plays a major role in business funding. At the end of the day banks and lenders still want to know, WHAT HAVE YOU DONE?
Lenders will review YOUR FINANCIAL HISTORY to judge your ability to repay when deciding whether they are willing to extend financing — especially for NEWER businesses or businesses that lack substantial revenue to stand on its own. The lender then expects YOU, the owner, to stand behind it.
Getting approved is only the beginning. Consistently making your payments on time and properly managing the credit extended to you is what builds credibility.
If your business isn’t consistently generating at least $10,000 per month, or if you can’t show that you’re capable of MANAGING $10,000+ on the PERSONAL SIDE — such as credit cards, auto loans, personal loans, student loans, or mortgage loans — or if you still have maxed out credit cards and collection accounts showing that YOU OWE MULTIPLE COMPANIES, ask yourself:
If this sounds like you, then you may need to rely heavily on your personal credit and a personal guarantee to qualify for certain types of business financing.
That said, Step 1 would be to position yourself to actually QUALIFY FOR A BUSINESS LOAN through a major financial institution. You would do this by focusing on removing any negative items and unnecessary inquiries from your credit report, while improving your credit scores to a 720+ and strengthening your personal credit profile to better position yourself for business financing.
This is where I come in. I’d be happy to help you through that process, and we can begin by scheduling a consultation to review your current credit situation and determine the best path forward.
My pricing is determined by the number of negative items appearing on your credit report, which means the total cost varies for each individual. To ensure accuracy and fairness, every client is required to book a consultation for $63 before receiving a personalized quote.
Consultation Breakdown:
• $30 covers the consultation itself, compensating me for my time and expertise
• $33 covers your enrollment in the credit monitoring service I use for all clients
Both are mandatory steps to begin the process.
If this arrangement does not work for you, I completely understand—however, it may mean we're not the best fit to work together at this time.
Sales Exception: During promotional periods or sales, the price will be set at one flat rate regardless of how many negative items appear on your report, and a consultation will not be required.
If you're serious about improving your credit, the first step is booking your consultation.
I completely understand why you may think that. I've personally been denied with a 750+ Credit Score with only ONE NEGATIVE ITEM. The hard truth is when banks & lenders do their background check on you IT'S NOT GOOD NEWS. Whether you have 2 negative items or 50. At the end of the day THE ANSWER SHOULD BE 0. This myth is actually one of the main reasons I recommend booking a consultation—because there's usually much more involved than what you see on the surface.
It's not about paying to remove ONE OR A FEW ITEMS. It's about the financial impact that item can have on your life and how much removing it could potentially save you. In many cases, the savings far exceed the investment.
Your Credit Report Is Always Worse On Paper Than In Real Life.
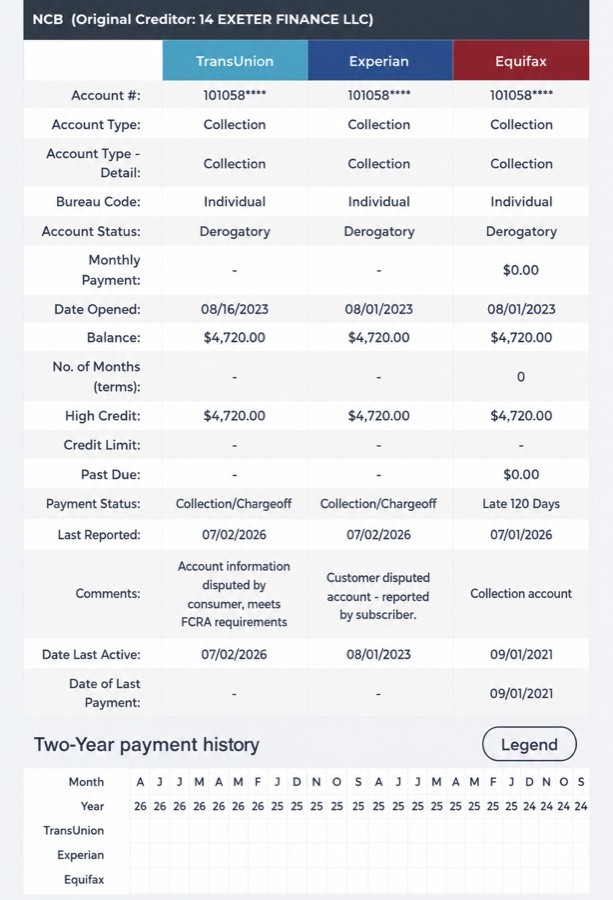
For example, you may see one collection account from EXETER FINANCE on your report. While that may be true in real life, that same account is often reporting to all three credit bureaus—Equifax, Experian, and TransUnion. On paper, that becomes three separate Collection accounts, because each bureau has to be addressed individually.
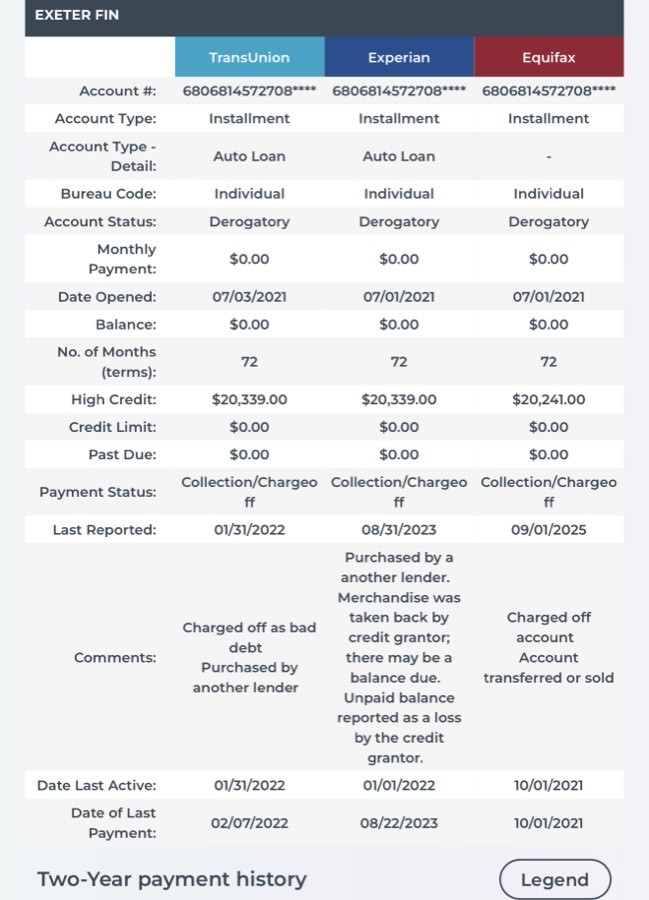
Now, if that account has been sold or assigned to a debt collector—such as NCB Group for example—since now both companies are reporting the same account, that's even more items that have to be addressed. So now that same 1 account has become 6 Collection Accounts ON PAPER. And unfortunately for you, we have to work from what's actually reporting on your credit file, not just what it appears to be at first glance.
The same applies to hard inquiries. If you have multiple hard inquiries on each bureau, that can also impact lending decisions. Many people think they only have one issue, but once we review the complete credit profile, there are often several factors working against them.
Also I would like to emphasize that just because you may have only 1 or a few items doesn't mean that it's still not a process. There's also a significant amount of work happening behind the scenes. My team and I spend time reviewing your reports, developing a strategy, preparing documentation, managing your file, and following up throughout the process. The fee covers both the expertise and the work required to give you the best chance at achieving results.
At the end of the day, I wouldn't focus on the PRICE—I'd focus on the VALUE.
No Matter The Price. The Investment has the potential to save you thousands of dollars in higher interest rates, loan denials, and missed financial opportunities. Credit repair isn't just another bill. It's an investment in your financial future.
I accept Afterpay, Klarna, and Zip as flexible payment options.
For clients requesting a traditional payment plan, I only accept payments through an invoice that allows you to securely place your card on file for automatic billing.
Important: To avoid any discrepancies or missed payments, I strongly recommend using a card that is not locked or restricted in any way. This ensures payments process smoothly and services continue without interruption.
When a payment agreement is established with a defined timeline, it is essential that the terms of that agreement are honored.
The fee charged covers the entire credit improvement process, not an individual dispute round. While payment plans are not required, one was extended as a courtesy.
If a scheduled payment is missed, all work on your account will be paused immediately, and no updates will be provided until the outstanding payment has been received.
If our team attempts to contact you regarding a missed payment and does not receive a response within 24 hours, the process will be fully suspended. In order to resume services, the remaining balance must be paid in full.
The amount you were charged represents the cost of the entire process. Any work completed up to that point is considered final and non-refundable.
This is similar to financing a vehicle. When you enter a financing agreement—for example, over a five-year term—you are expected to fulfill the agreed-upon payments for the duration of that contract.
Even if you make payments consistently for 3 years, failure to continue those payments can result in consequences such as the vehicle being disabled (in some newer models), repossession, and potential negative reporting to your credit.
The payments already made are not refunded, as they covered the time and usage of the vehicle during that period.
Now granted you're not buying a car, but I expect the same level of respect for my business. You wouldn't call the dealership and mention how you've already made payments for 3 years in a row. Because you understand you've broken the agreement so they no longer have to give you access.
Likewise, in this process, payments made reflect the services rendered up to that point. Therefore, they are not eligible for reimbursement, And I am not required to continue service at that point.
Once services have been stopped due to missing payments—the remaining balance must be PAID IN FULL, In order to resume services.
These policies are not personal. They are necessary to protect the integrity of our business operations and ensure fairness across all client accounts.
If you are not payment ready THAT IS OK!
Communication is everything. All you have to say is you need more time, you changed your mind, or you’re exploring your options. At the end of the day I can’t force you to get started, and you don’t have to work with me if you don’t want to. I understand that. 🤷🏾♂️
You do not have to feel like you wasted my time. Especially if you paid me for a consultation because I have been paid for my time.
My thing is I don’t reach out to NOBODY FIRST. So once you inbox me I assume you’re serious & you have now stepped into my world. So yes I will follow up with you. But I AM NOT A DEBT COLLECTOR. I WILL NOT BE MAD if you’re not payment ready or don’t want to move forward.
All I ask is that you PLEASE DON’T IGNORE ME. Communication is extremely important, and I believe that’s fair.
For example, let’s say a month from now you’re actually payment ready to move forward and you reach out to me. If I ignored you when you were serious and ready to get started, you would rightfully feel like I was being unprofessional. So let’s just both stay professional.
I completely understand if you need more time or if you’re not ready right now—or even if you may feel like we’re not the best fit. Just communicate that with me. That’s all I ask.
Keep in mind I accept Afterpay & Klarna & Link. (EBT is not an option during sales.)
Your credit transformation journey begins with a strategic consultation. Book your personalized session to discuss your current credit situation, explore your goals, and map the precise path to achieve exceptional results.
The consultation fee is $63 which covers:
$63
One-time consultation fee to begin your credit repair journey
IMPORTANT:
After you make the payment it will automatically redirect you to my booking link. PLEASE READ THE DESCRIPTION IN THE BOOKING LINK AND DO THAT PART FIRST‼
Once that part is completed you can then finish filling out the questionnaire to book your appointment.
Please choose the best time where you will have the LEAST AMOUNT OF DISTRACTIONS.
Talk to you soon! 🙌
Important Consultation Guidelines:
• All Consultations Are NON-REFUNDABLE
• You will be granted a 5 minute GRACE PERIOD. Anything after that will put me behind for the day and we will be forced to reschedule.
• If you need to reschedule, please let me know ahead of time.
• You may RESCHEDULE for FREE but a NO-CALL-NO-SHOW will result in a $50 Fee for your next appointment.
Setting Expectations:
I understand you may feel like “you already know how this works” or “you don’t need this part.” However, there is a huge difference between KNOWING AND UNDERSTANDING. 97% of my clients come to me for help, which means there is something holding them back—otherwise, they wouldn’t be here.
Additionally, over 70% of Americans struggle with their credit, and that statistic cannot be ignored. Because of this, I approach every consultation as if you are starting from zero, ensuring nothing is overlooked.
How the Process Works:
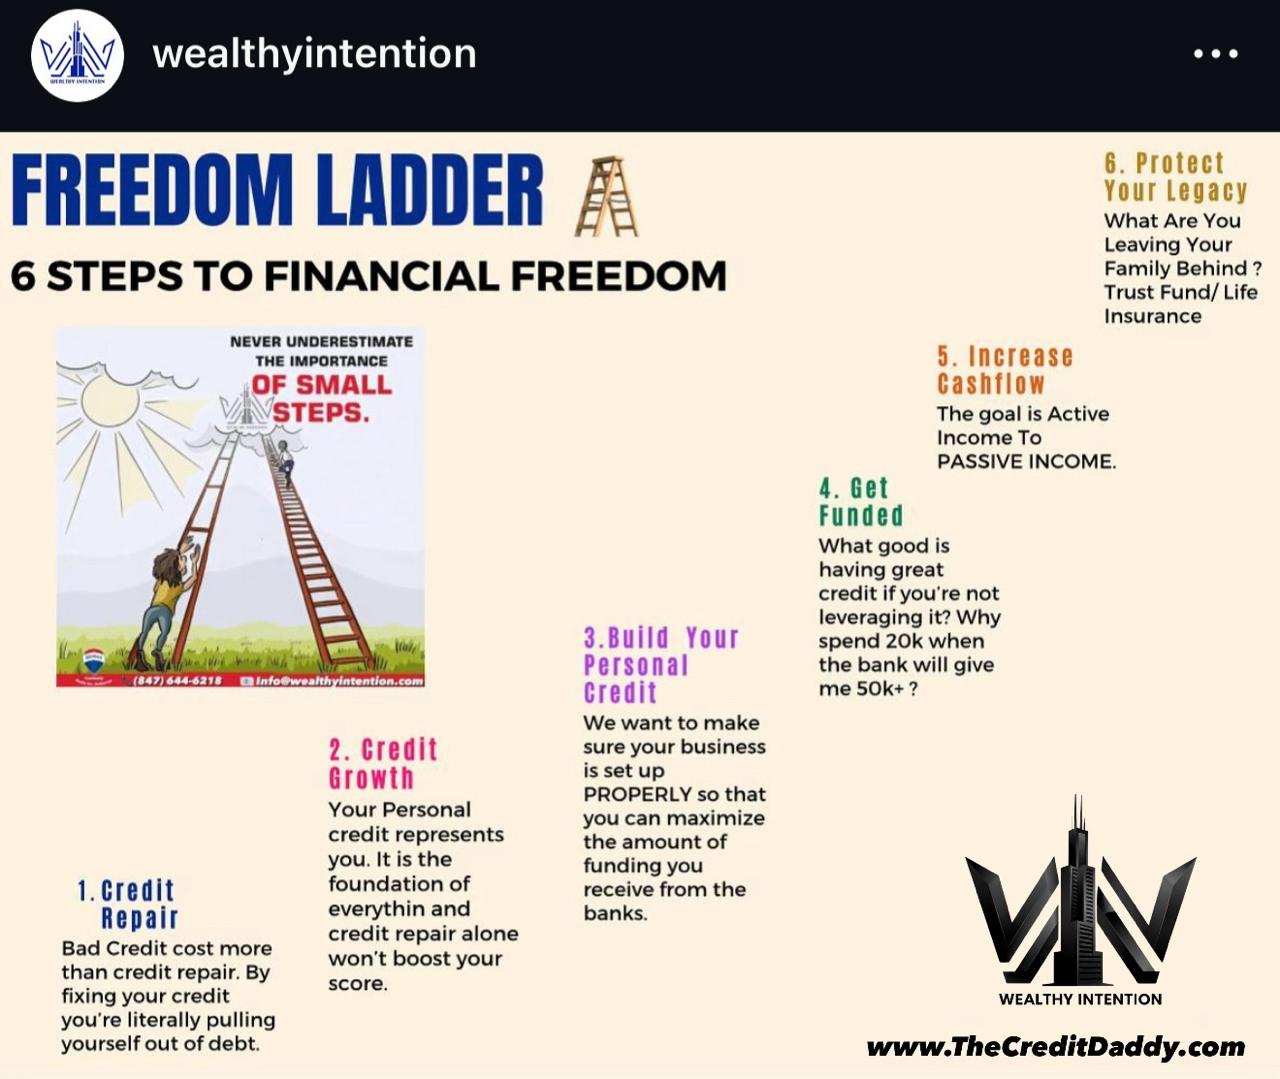
Step 1: Credit Repair
My primary responsibility is to dispute inaccurate, unverifiable, and negative items on your credit report. That is the service you are paying for.
Step 2: Credit Growth
In addition, I provide all clients with guidance on how to properly build and maintain their credit scores by giving them a TO DO LIST.
Step 3: Profile Building
I also coach clients on how to develop a strong credit profile and assist with applying for credit cards when the timing is appropriate. THIS IS ALSO INCORPORATED WITHIN THE TO DO LIST.
Step 4: Execution
This is when I assist clients who are ready to pursue business funding or apply for major financing such as a home or vehicle. While this level of involvement is not required of me, I choose to provide it because I genuinely care about my clients' long-term success.
It's important to understand that a 750 credit score alone does not automatically mean you have GOOD CREDIT. True credit strength consists of:
Step 5: LLC Setup / Business Funding (BONUS)
Regarding business credit, I educate clients on how to properly set up an LLC, establish relationships with banks, and position themselves to qualify for business funding. My goal is to teach clients how to apply independently. However, if you choose to have me assist directly with applications, I charge a 10% success fee based on the approved amount.
I also work with relationship managers at major institutions, including Chase, U.S. Bank, PNC Bank, Truist, Citizens Bank, the SBA, and American Express. These relationship managers are the individuals who actually review and approve applications, and I refer my clients directly to them. Additionally, I offer tradelines & shelf corporations, which function similarly to tradelines but for an LLC.
Step 6: FREE FINANCIAL REVIEW 👀🔎
Our Wealth Management team is providing a FREE Financial Review with a financial advisor as a client benefit!
Services include:
All Of steps 1-6 are included but understand what you are paying for is Step 1: CREDIT REPAIR — the process of cleaning and correcting your CREDIT REPORT. When it comes to creditworthiness, your credit report is what gets you approved — not your credit score.
I can't give a specific timeframe for a few reasons:
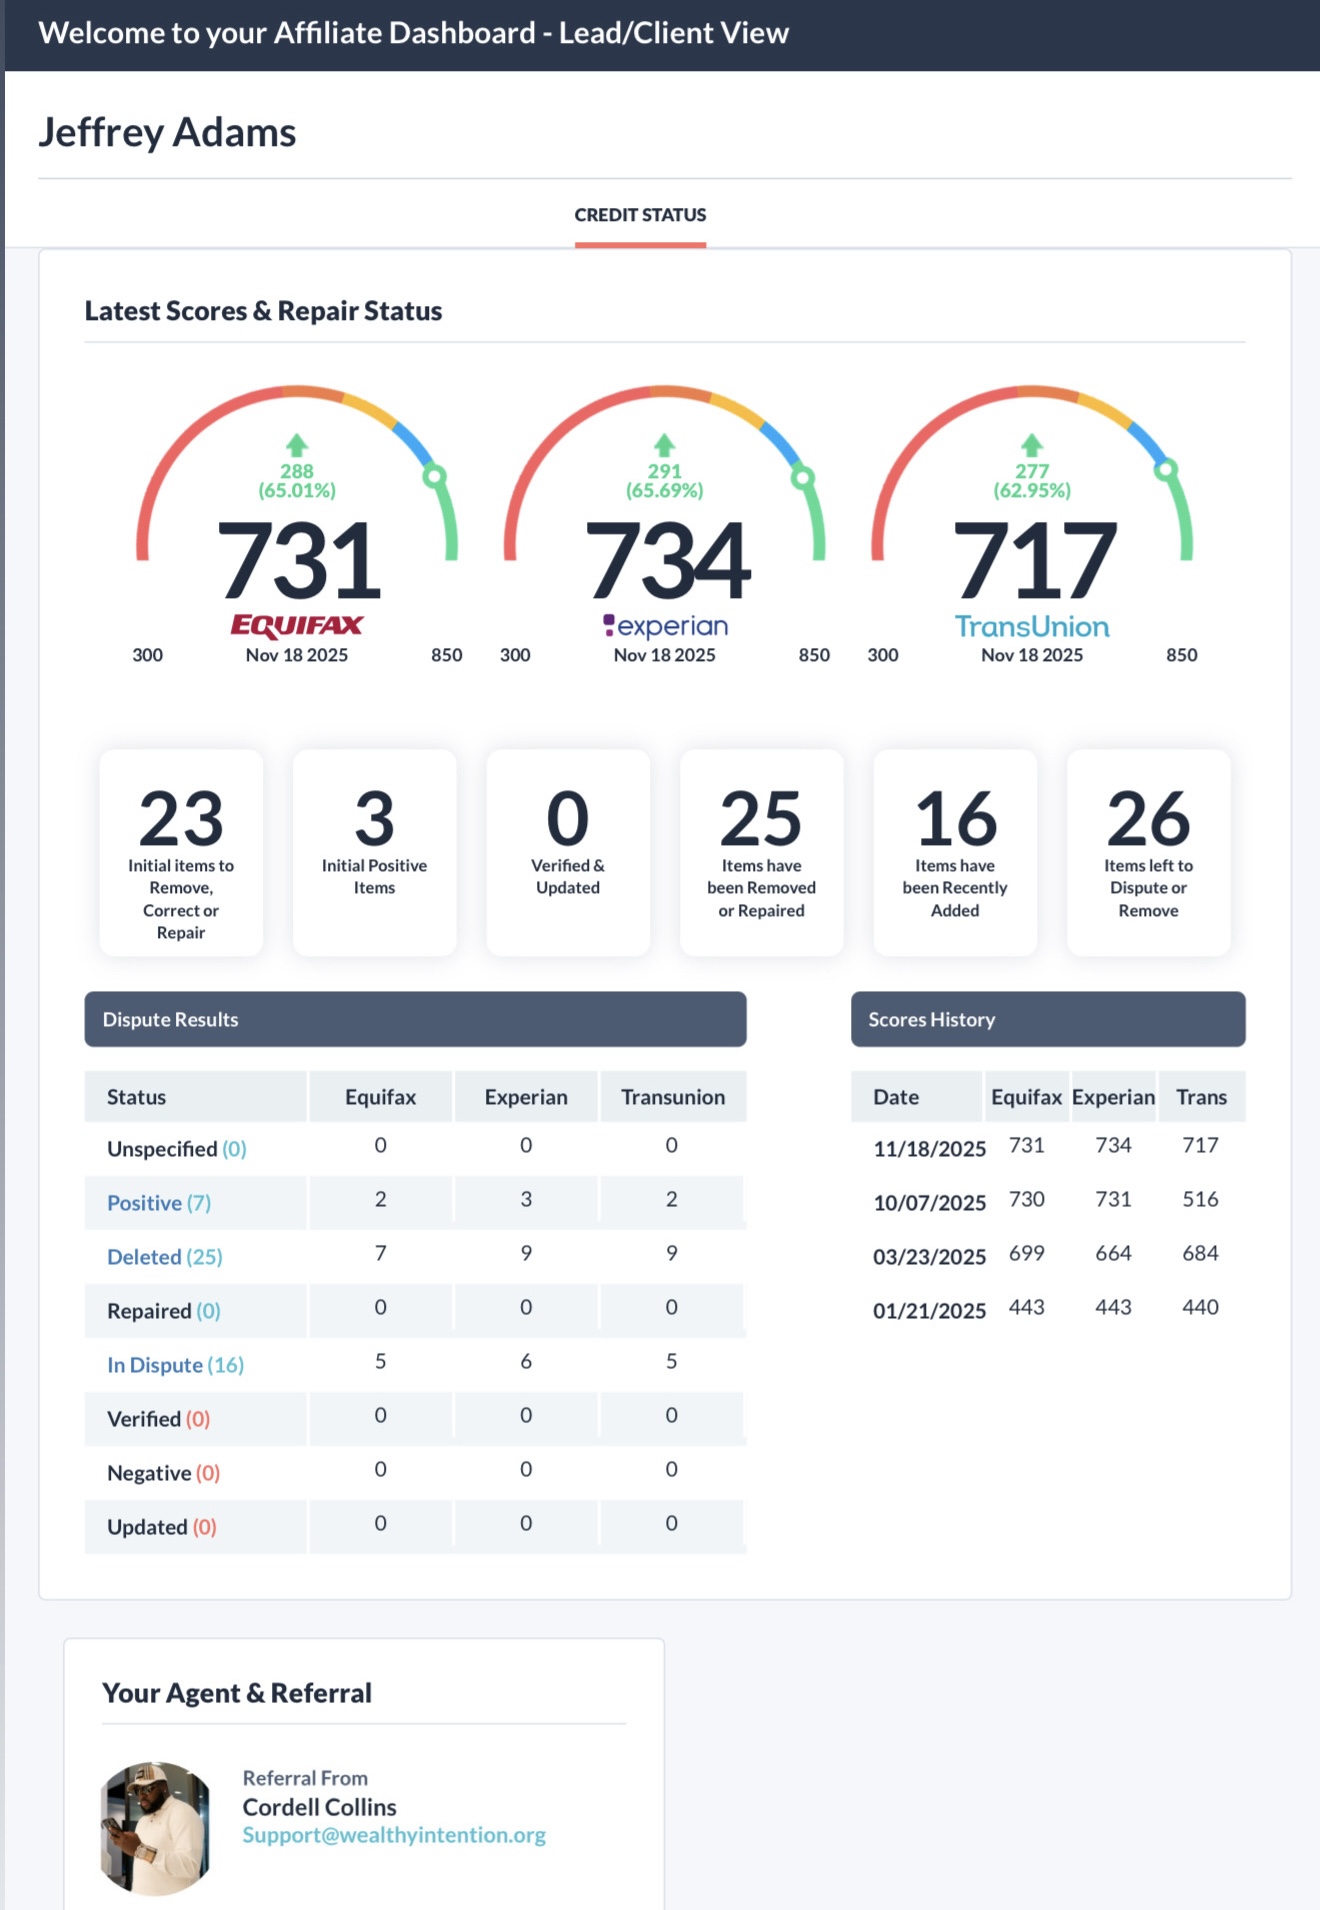
If you look at the screenshot above, you'll see that this client started with 23 negative items and we actually got 25 negative items deleted. Which means 2 additional negative items appeared after he started, and we got those removed as well — resulting in a completely clean credit report.
If you pay attention to the dates on the right-hand side, you'll see this client started Round 1 on 1-21-25 and Round 2 on 3-23-25. However, the next round did not begin until 10-7-25. From the outside looking in, it may appear that no work was done for 8 months, but that is not the case.
In most situations, delays like this happen because the client either did not maintain their credit monitoring subscription (which prevents me from accessing your credit report), or the client failed to submit an updated Proof of Address (POA) every single month.
Please understand, every time dispute letters are sent, we must verify your identity. Your Proof of Address is required for every round, and if it is not provided, I cannot proceed with the next round of disputes.
These two things alone can prolong a client's results for months or even up to a year — which would not be my fault as long as I send out emails and texts notifying them. So his total timeframe took a total of 10 months. 10 months, although it could have potentially been significantly shorter without delays.
On top of that, the credit repair timeline varies from person to person, depending on the number and type of negative items on the credit report.
• Fastest deletion: Eviction removed in just 14 days
• Quickest full clean-up: 88 total negative items cleared within 45 days
That said, results like these are possible but not typical and cannot be guaranteed for every client — no one in this industry can honestly make such a promise. If they do, they're telling you what you want to hear so you feel comfortable enough to give them your money because they know you're in a rush & most likely desperate.
Realistic Expectations:
On average, credit repair takes 6 to 9 months, and in more severe cases, it can take up to a year.
I believe in full transparency: credit repair should take as long as it needs to take. Anyone guaranteeing complete results in 30–60 days is not being realistic. The average client goes through 4–7 rounds of disputes. If it were that simple, multiple rounds of disputes wouldn't even exist.
Unfortunately, many companies lie for sales, which gives credit specialists a bad reputation. My approach is different — I prefer honesty over hype. MY NAME IS MORE IMPORTANT THAN YOUR MONEY! I will let anyone walk before I tell them what they want to hear. It's not about what you want — it's about how the process actually works. Results take time, but they do come. Will it take the full 6–9 months, or even a year? Not necessarily, but you should be prepared for that timeframe.
Each dispute round lasts approximately 45 days, and after every round, you will receive a detailed PDF update outlining any deletions or changes that occurred.
See Real Results:
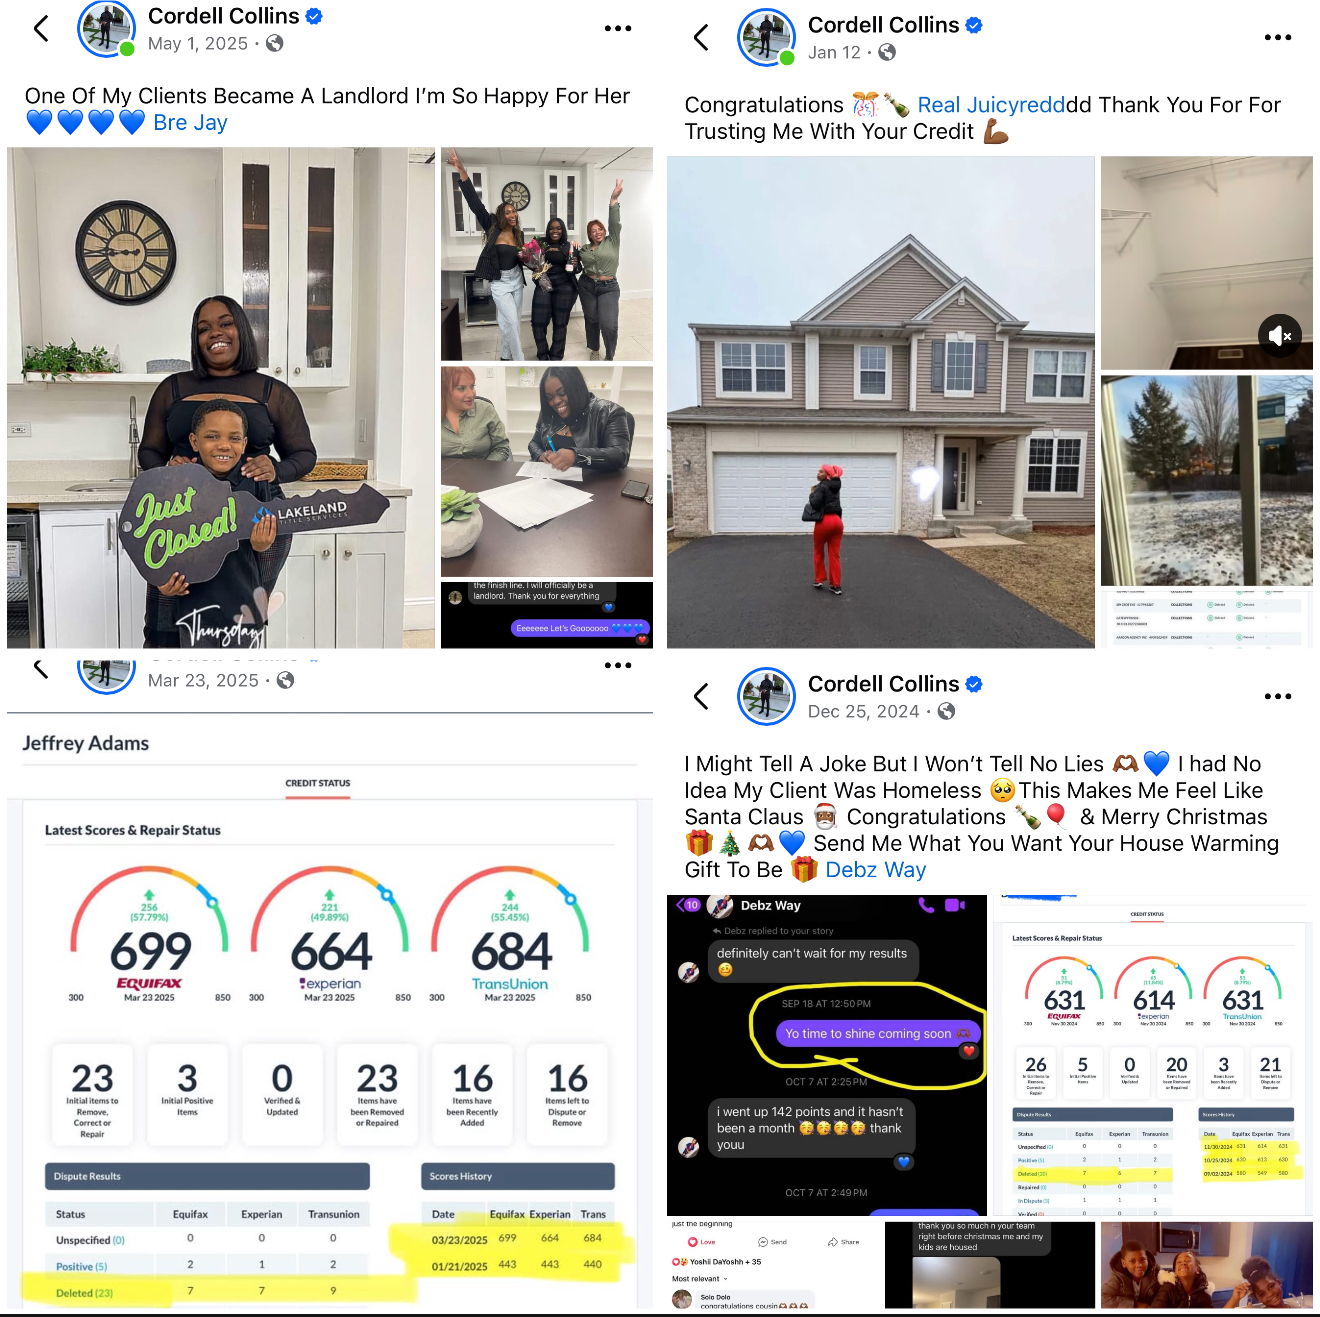
If you click this link you can look at the credit scores and deletions for some of my clients and kind of do the math on how long it took — do with that what you will. Also, a lot of the shares are from some of my real clients.
www.TheCreditDaddy.com/results
Individual Inquiry Removal: $50 per inquiry
24 Hour Inquiry Removal: $150
When you begin the credit repair process, my goal is to dispute and address all negative items currently listed on your credit report. If new negative items appear during the process - such as new collections, inquiries, or late payments - please understand that I am not required to work on those new items. However, I do understand that there is a difference between an old account appearing later than expected vs applying for things & adding new inquiries or late payments.
As part of my service process, if a new collection account appears or a previously deleted collection reappears while you are actively enrolled in the credit repair program, it will automatically be included in the next dispute round at NO ADDITIONAL COST. That said, this is a professional courtesy, not an obligation. I handle it this way in good faith to help keep all clients on track and maintain the progress of their credit profile.
After Program Completion:
Once all negative items have been removed and your file has been successfully completed and closed, the service is considered finished. If a collection account later appears or reappears after the completion of the program, there will be a $300 reactivation fee to reinitiate credit repair services.
To set clear expectations:
Again. I understand life happens. If you absolutely can’t wait until we are done with the process. I cannot force you to wait. Search for “ When can I start applying for things “ And also search for “ How To Avoid Unnecessary Inquiries “ this should at least let you know if you have a chance of approval.
If you need further assistance don’t hesitate to Book an appointment. This ensures we stay aligned, protect your credit, and avoid setbacks in your results. My goal is to deliver strong results, and that requires us to work together strategically.
If we’ve already discussed the importance of keeping your accounts positive and you continue to receive new inquiries or negative items, an additional charge may apply for continued credit repair services.
If I decide to charge for additional work, I will inform you first and ask whether you wish to move forward.
If you choose not to, all work on your file will be paused or stopped entirely. Repeatedly applying for new credit while your disputes are in progress adds unnecessary inquiries, lowers your scores, works against your progress, and creates additional work that makes my team’s job significantly harder.
Why can’t we just continue to dispute your original negative accounts?
Realistically it wouldn’t matter. If it has got to this point we would be simply working backwards. You still have more negative items and every new inquiry lowers your scores even more. This extends the overall timeframe and it also makes me look like I’m not doing my job. Then the first thing you would say as a client is “ I’ve been working with him for 2 years and I haven’t gotten any results” I simply can’t have that. Especially if you were the problem. Respectfully.
At Wealthy Intention, we value every client and are committed to providing high-quality, consistent service. To maintain efficiency and ensure fairness to all active clients, we’ve implemented the following Inactive Client Policy:
Inactive Client Policy
Clients who have been inactive for 60 days or more—meaning no response to messages, no document submissions, or no engagement with our support team—will be considered inactive and temporarily removed from our active client roster.
Please note that multiple reminders via email and text are sent before an account becomes inactive. We understand that life happens-unexpected events, busy schedules, and personal matters can sometimes take priority. That’s why we send multiple reminders before marking any account as inactive. Even if you communicate the reason you are unable to maintain your credit monitoring subscription, or upload certain documents, it does not eliminate the issues associated with becoming an inactive client. If your account becomes inactive as a result, your file may still be subject to the $300 reactivation fee in order to resume services.
At the end of the day Credit repair is a collaborative process. Not only were you informed on my website about the things that can delay the process and make you become inactive. We also sent out multiple email & text reminders. When clients go silent or no action is taken after repeated contact attempts, it affects our ability to manage our workload efficiently. It creates workflow and scheduling challenges for our team and backend systems. This policy ensures that active, engaged clients receive the attention and priority they deserve.
Your Profile Is Costing Us Money
While an account is inactive, we are unable to continue work on the credit profile. However, we must still retain a client’s file records of what was disputed or deleted in case a client later requests updates or verification of prior activity before becoming inactive. Which requires us to maintain your profile in our system and preserve all past correspondence, which results in monthly fees. Also storage costs for backed up emails and text for keeping old conversations for proof that reminders have been sent out. So in conclusion Even when no active work is being performed. We still have to pay for your files unless we delete all history.
To reactivate your account and resume services, there is a $300 Reactivation Fee. This fee covers administrative time, file review, and re-entry into our system.
For your convenience, we proudly accept Afterpay, & Klarna as flexible payment options.
Once the reactivation fee is completed, your account will be restored, and we will promptly continue your service process.
If you have any questions or would like to reactivate your account, please contact our support team at support@wealthyintention.org or text (312) 584-9969.
We are committed to providing professional, compliant, and results-driven credit services. Because credit improvement is a process that requires time, consistency, and client cooperation, the following refund policy applies to all clients.
100% Money-Back Guarantee
If a client completes four (4) full rounds of disputes as outlined in their service plan and receives zero (0) deletions, a 100% refund of the Service charge paid for credit repair only will be issued. (this does not include the $33/month for your credit monitoring) This guarantee applies only when all program requirements and guidelines have been fully followed by the client.
Once services have started, no refunds will be issued due to a change of mind. If you are someone who's married or typically makes decisions with your partner, Please ensure you have discussed this decision with your spouse or decision-maker PRIOR to payment completion.
If you choose to stop services before completion, that is your right; however, no refund will be issued if you do not allow us to complete the agreed-upon process. I shall only be responsible for a refund if I DID NOT DO MY JOB. Not because someone stopped me from doing my job which is get you DELETIONS.
Refunds will not be issued if the client interferes with the credit repair process or fails to follow required guidelines, including but not limited to:
Any work completed up to that point will be considered final and non-refundable.
You can't pay for credit repair then:
Then come back 3 months later saying you haven't heard anything, seen any changes, requesting a refund, & proceed to blame my company or the process.
Credit repair works only when WE work.
I'm not a miracle worker, I'm a strategist. You have to do your part as well.
Please take your credit seriously-it represents your financial credibility.
Fairness & Accountability: This policy exists to ensure fairness and accountability for both parties. Our goal is to help you rebuild and protect your credit, but success requires active participation, honesty, and cooperation from the client.
Once again. I shall only be responsible for a refund if I DID NOT DO MY JOB. Not because someone stopped me from doing my job which is get you DELETIONS.
ChexSystems is a consumer reporting agency that banks and credit unions use to decide whether to approve or deny you for checking and savings accounts.
It's like a credit report—but for bank accounts, not loans or credit cards.
ChexSystems collects information about negative banking activity, including:
It does NOT track credit cards, loans, or credit scores.
If you have negative info in ChexSystems, banks may:
This is why people say: "My credit is good, but the bank still denied me."
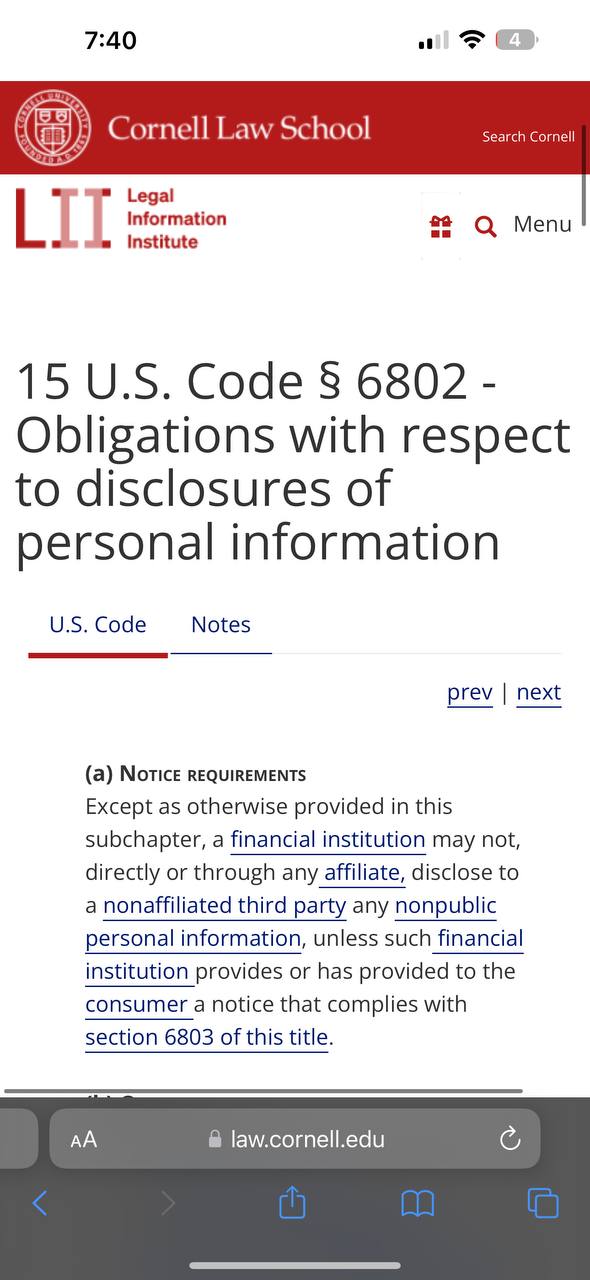
If you are in chexsystems or early warning then that means that you have been violated. Read 15 USC 6802- 15 USC 6805. If you read your terms and conditions and privacy agreements of your credit card accounts banking information it tells you that they do not share your personal information with any 3rd party non affiliate….
Third Party Non-Affiliates Include:
What we don't realize it when we open up these accounts we have the option to opt out so they don't share our information but they don't out right tell us that in plain English either. But in there privacy agreements and terms and conditions it states that they don't but yet they do anyway which is a violation.
Early Warning Services (often just called Early Warning or EWS) is a consumer reporting agency used by banks to decide whether to approve you for checking and savings accounts and to monitor for fraud.
It's similar to ChexSystems—but more powerful—and is heavily used by major banks.
Early Warning Services collects:
Unlike ChexSystems, Early Warning is often real-time and behavior-based.
If you are in ChexSystems or Early Warning then that means that you have been violated. Read 15 USC 6802 - 15 USC 6805. If you read your terms and conditions and privacy agreements of your credit card accounts and banking information, it tells you that they do not share your personal information with any 3rd party non-affiliate…
Third Party Non-Affiliates Include:
• Lexis Nexis
• Experian
• Equifax
• Transunion
• Early Warning System
• ChexSystems
What we don't realize is when we open up these accounts, we have the option to opt out so they don't share our information — but they don't outright tell us that in plain English either. In their privacy agreements and terms and conditions, it states that they don't share your info, but yet they do anyway, which is a violation.
Request your consumer report from both websites & send me over the PDFs once you receive them.
ChexSystems:
https://www.chexsystems.com/request-reports/consumer-disclosure
Early Warnings:
https://www.earlywarning.com/faqs-requesting-your-file-disclosure
ChexSystems Customer Service: 800-428-9623
Early Warnings Customer Service: 800-745-1560
Representatives are available to assist during normal business hours 8AM to 7PM Central Time, Monday - Friday excluding federal holidays.
Payment Requirements:
• Payments must be paid IN FULL before we begin the process
• Afterpay, Klarna, and Zip are acceptable
After that, we will mark up any information you do not recognize or whatever is negative and start the disputing process. This process can take up to 3 months.
Credit Repair DOES NOT DELETE THE DEBT! — it only removes inaccurate, unverifiable, or outdated negative items from your credit report. However it is still important.
Think of it like a record expungement: the event happened, but lenders can no longer see it when reviewing your credit. This allows you to qualify for approvals you may have been denied before.
Important to Understand:
You may still owe the original creditor, and it would be smart to settle with them after the deletion—especially since most companies would require payment or settlement if you want to do business with them again.
However, once the item is removed from your report, it no longer holds you back from getting approved by other companies when viewing your credit report.
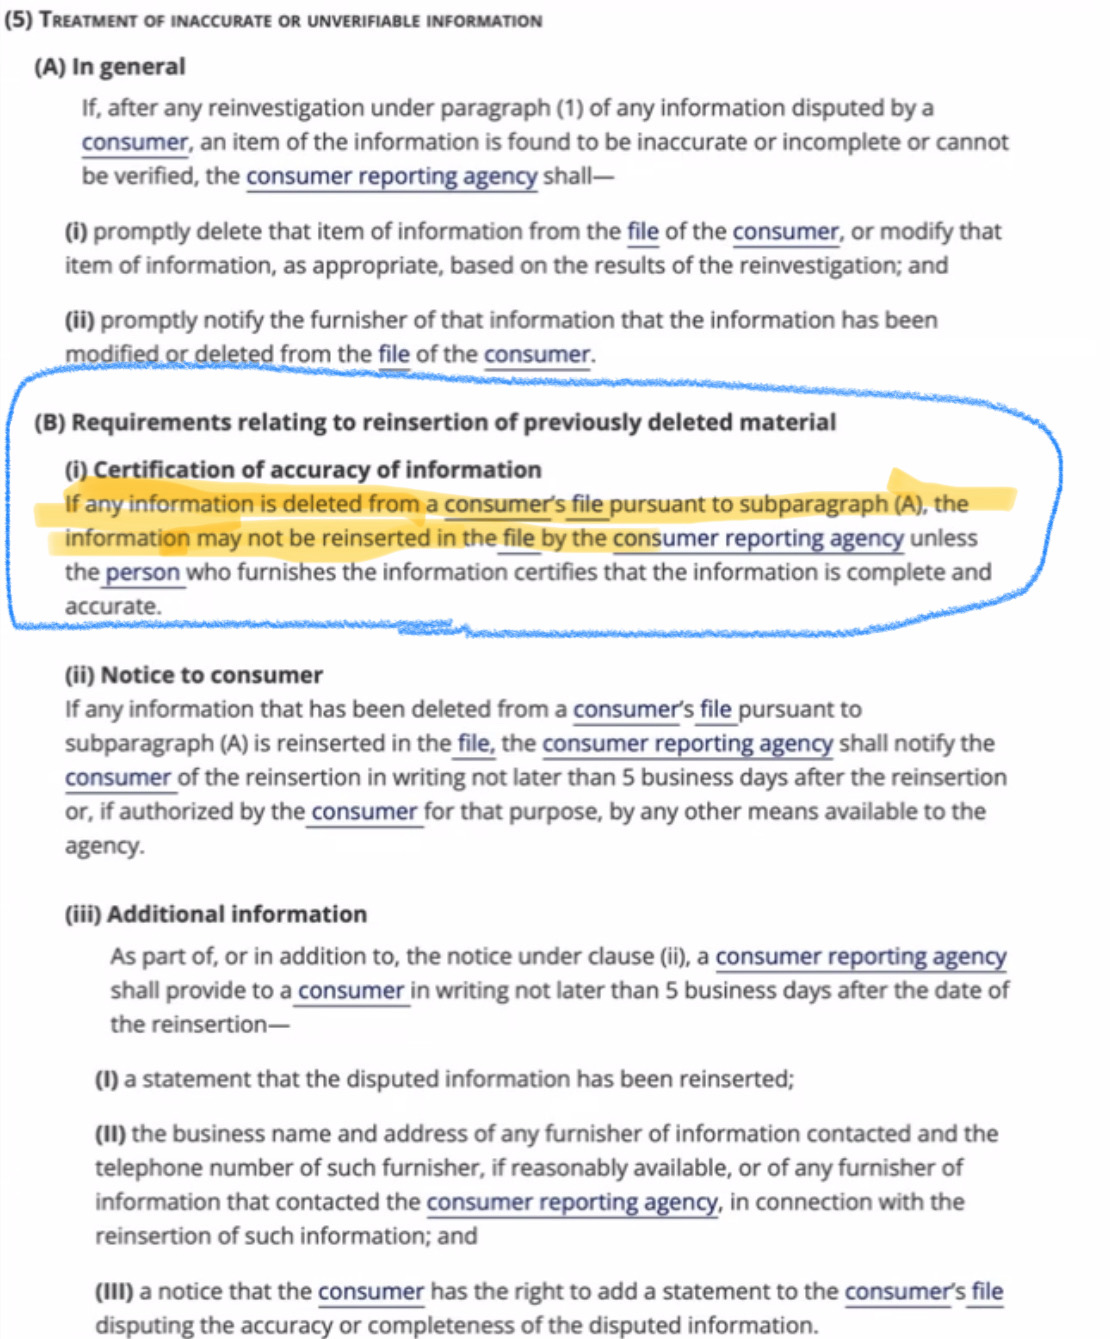
Once an item has been deleted from your credit report, the credit bureaus are not supposed to reinsert it. However, in some cases, if the debt remains unsettled, a creditor or collection agency may attempt to re-report the account—often assuming that consumers are unaware of their rights under the Fair Credit Reporting Act (FCRA).
Active Client Protection: If you are an active client and a previously deleted item reappears, we will dispute it again at no additional charge during your next dispute round.
After Program Completion: If you've completed your program and chose not to settle the debt, and the item later reappears, there will be a fee to reinitiate credit repair services—especially since you are being informed upfront about the possibility of re-reporting.
Debt-to-Income Ratio (DTI) is a simple but very important number lenders use to decide whether to approve you, how much to approve, and what terms you get.
Your DTI is the percentage of your gross monthly income that goes toward monthly debt payments.
In short: It tells lenders how much of your income is already spoken for.
Formula: Total Monthly Debt ÷ Gross Monthly Income × 100 = DTI%
These two terms sound similar but they measure completely different things on your credit report. Understanding the difference is key to understanding your credit score.
FREE GAME ✍🏾 Bold Wordings = What Banks & Lenders Like To See 👏🏾
It answers the question: How Often Do You Pay Your Bills On Time when you owe?
Is It 20%, 50%, 80% Or 100% Of The Time? Meaning You Pay Your Bills On Time Every Month?
Payment History is the most important factor in your credit score.
It answers the question: How Long Have You Been Establishing Credit?
Has It Been For 3 Months, 6 Months, 1 Year, 3 Years, Or 5 YEARS OR MORE?
• Calculated based on the average age of all your accounts
• Older = better for your score
Together, these two factors alone count for 50% of your total credit score.
❌ Why You Usually Should NOT Close Unused Credit Cards
Closing a credit card can hurt your credit, even if you never use it.
1️⃣ It Can Increase Your Utilization (30% of your score)
Credit utilization = balances ÷ total available credit.
Example:
👉 Score can drop without you doing anything wrong.
2️⃣ It Can Lower Your Average Credit Age (15% of your score)
Older accounts help your profile.
3️⃣ Banks & Lenders Like to See Available Credit
Banks prefer:
Unused cards = strength, not weakness.
✅ When It DOES Make Sense to Close a Card
You might consider closing a card if:
💡 Pro Tip: Before closing, ask the bank to:
🧠 Best Practice — What I Recommend to Clients
This keeps the account active without increasing utilization.
In Conclusion: Avoid Closing Accounts.
Nothing wrong with settling a debt. It's just WHEN you settle it. Please allow me to explain.
9/10 if you have a collection, your information has been passed on to a 3rd party debt collector that you NEVER did business with — so therefore you DO NOT OWE THEM ‼️
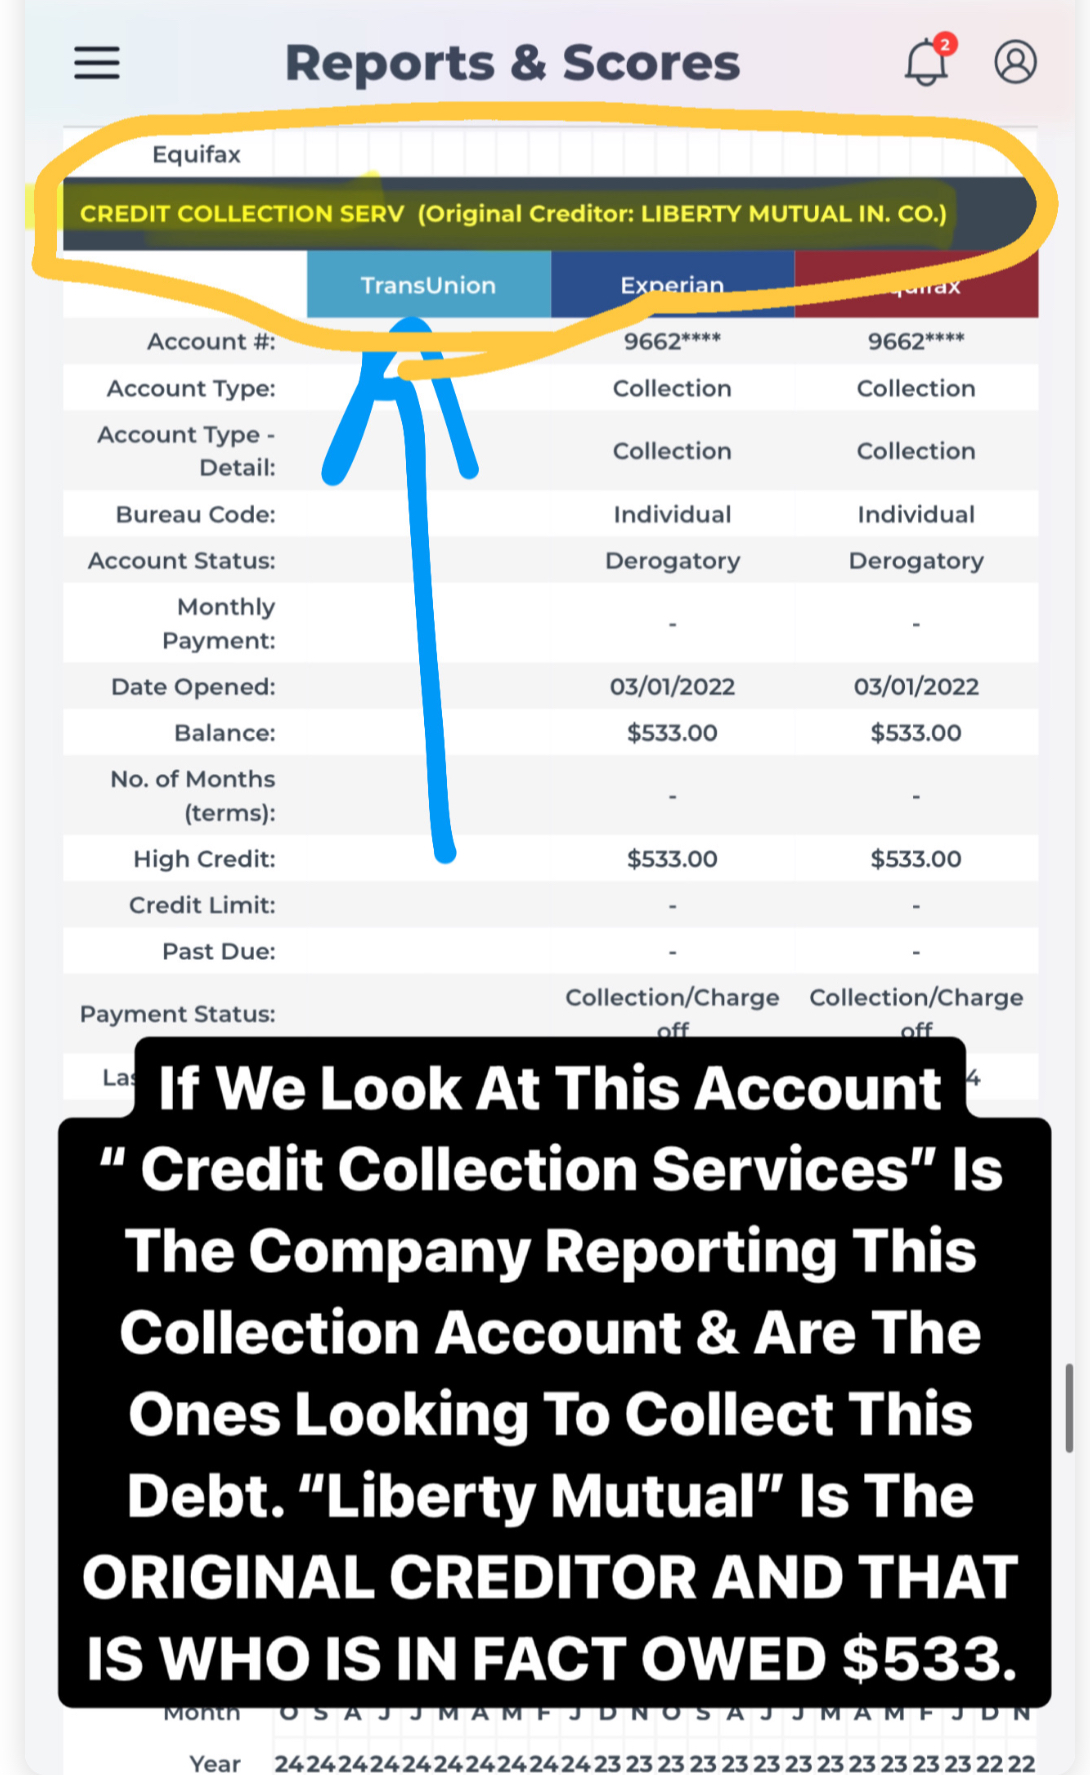
Why pay a company you don't owe?
Even if it were the original creditor, paying them DOES NOT REMOVE IT FROM YOUR CREDIT REPORT.
Every state has a statute of limitations on when a creditor can collect on a debt 💸. A lot of times consumers don't realize they're almost scot-free of paying a debt — but when they make a small payment, THE CLOCK STARTS OVER.
If you fall for that letter saying "Pay 30-40% off and we will SETTLE this for you," it will still be on your credit report as a Paid Collection / SETTLED FOR LESS THAN FULL BALANCE — which is still a negative account and DOES NOT help you.
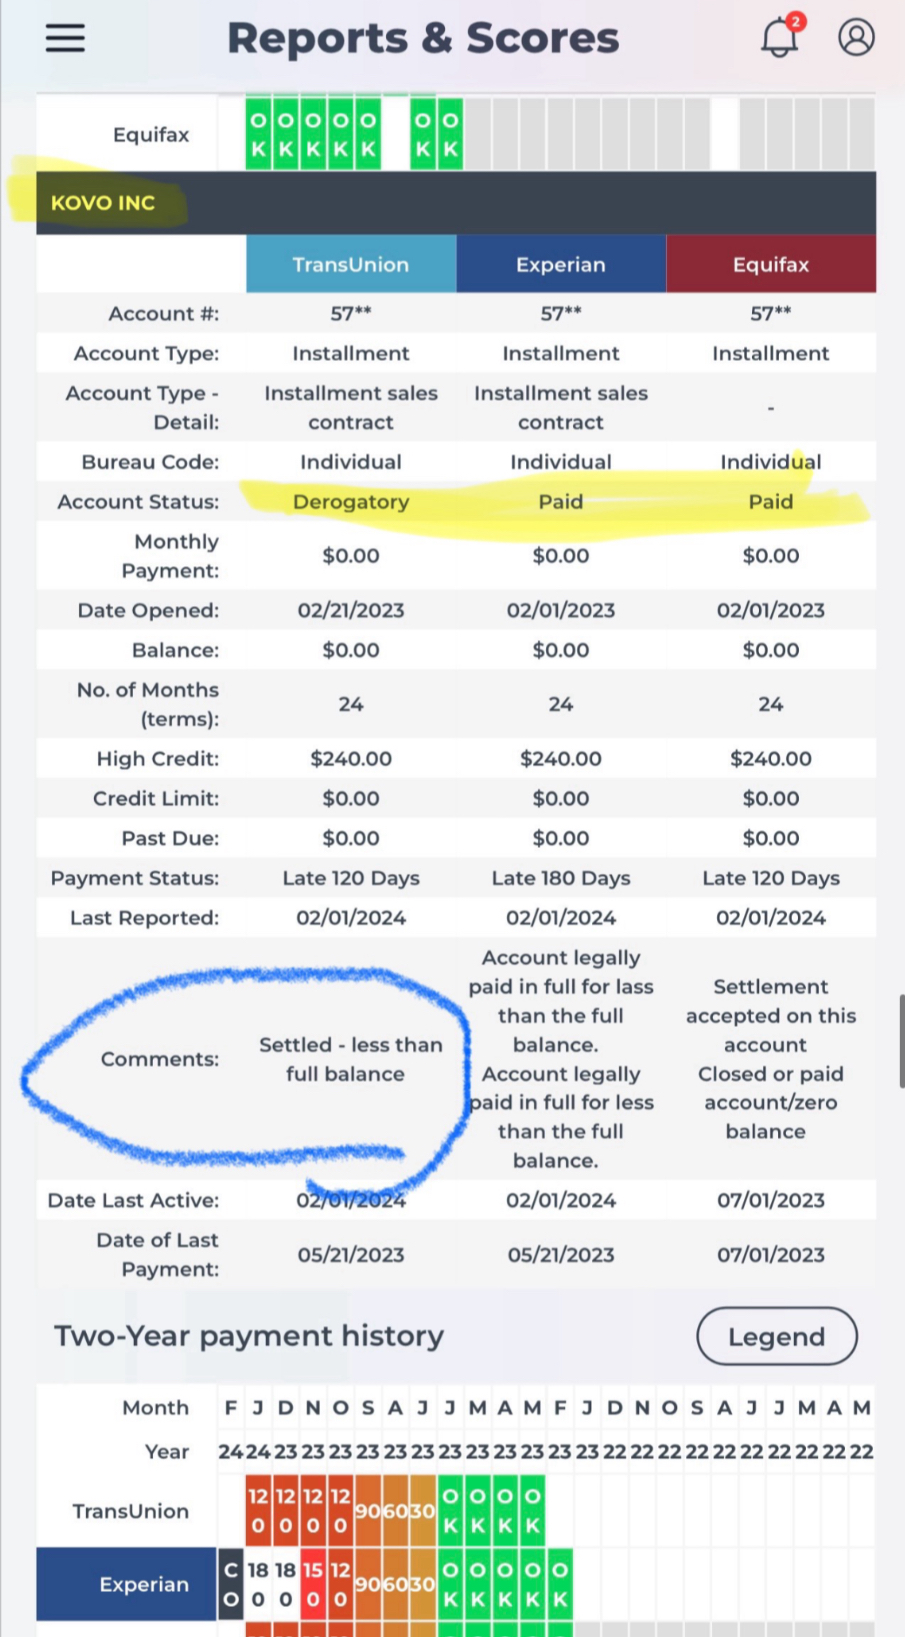
Not only were you already behind 120-180 days, but when you finally decided to pay them, they didn't even get all of their money? It doesn't look good.
If you pay them IN FULL, it will still show up as a PAID COLLECTION — which is still a negative account and DOES NOT help you.
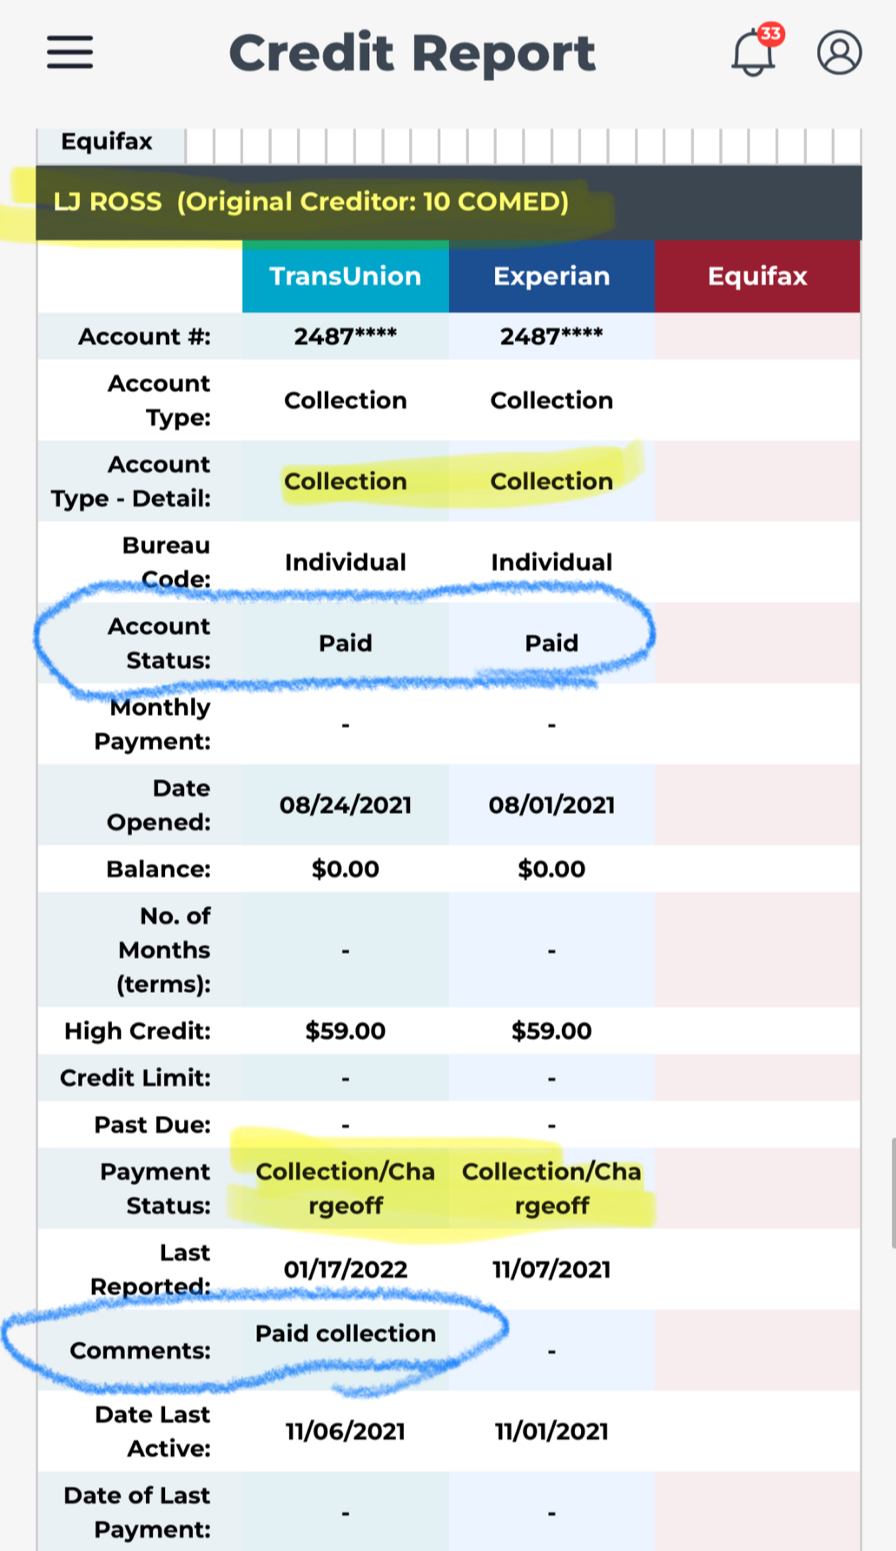
Short Answer: Paying a collection DOES NOT HELP YOUR CREDIBILITY.
Example: I go to jail for stealing money out of Walmart's register. I do my time for it. When I get out of jail, I apply to work for Chase Bank. Do you think they'll hire me? I can't say "But I went to jail for it" because something like that should never have happened to begin with.
No different here. How the banks look at you: if you defaulted on your agreement several times already, what makes this time different? Would you continuously lend money to someone who never pays back on time?
Each state sets different time limits for different categories of debt. The clock doesn't run the same for everything.
Common Debt Categories That Matter (Illinois Example)
| Debt Type | Why It Matters | Statute Of Limitations |
|---|---|---|
| Written contracts | Credit cards, personal loans, auto loans | 10 years |
| Oral (verbal) contracts | Handshake agreements | 5 years |
| Open-ended accounts | Credit cards, lines of credit | 5 years (commonly argued) |
| Promissory notes | Student loans, auto loans, personal loans, installment loans | 10 years |
| Judgments | Court-ordered debts (completely different rules) | 7 years (renewable) |
Each category can have a different statute — even within the same state.
What Starts The Clock? The statute of limitations clock usually starts at:
⚠️ Any of the following can RESET the clock:
If the statute of limitations has already surpassed, the only thing you really need to do is get the negative item deleted from your credit report so other lenders won't see the debt.
A lot of times consumers don't realize they're almost scot-free of paying a debt. When creditors & debt collectors convince you to get on a payment plan and you make that first small payment, THE CLOCK STARTS OVER.
This is why clients should NEVER casually agree to pay old debt without advice. If you pay them, it will be harder to get removed because now you look guilty. Why would anyone pay a debt that doesn't belong to them?
You may receive letters & emails threatening to garnish your check or sue. It's all a bluff to scare you into paying.
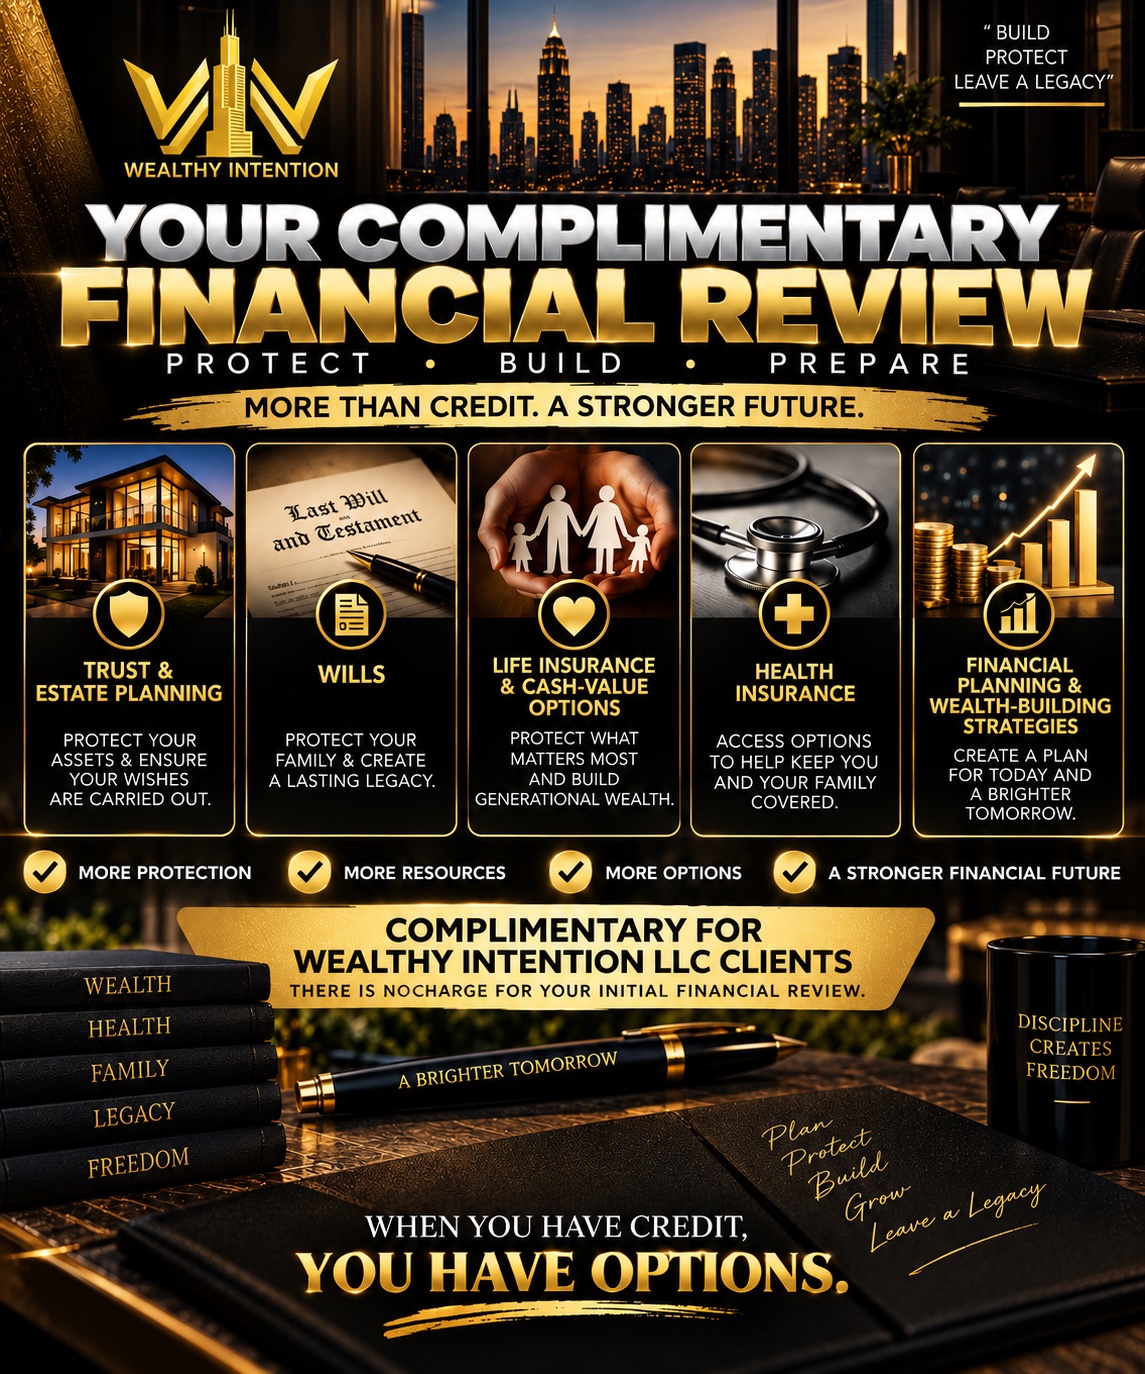
At Wealthy Intention we want to provide our clients with additional financial resources and services.
🎉 As a Wealthy Intention LLC client, you now qualify for a FREE Financial Review! With a LICENSED FINANCIAL ADVISOR
Our partnered Wealth Management team will review your financial needs and goals and introduce you to resources that may help you protect, build, and prepare for your financial future.
Services include:
There is NO CHARGE for your initial Financial Review as part of this added client benefit.
and EXPECT A CALL SOON FROM: 754-218-5910
THIS IS NOT MANDATORY and there is Absolutely — no pressure at all! Even if you already have life insurance, a will, trust, health insurance, or other financial plans in place, it can still be beneficial to periodically review them to make sure everything is not only SET UP PROPERLY, but that they all are actually WORKING TOGETHER as part of your overall financial plan.
Understand you can have all of these things in place. But if they are not ACTIVELY WORKING TOGETHER, it’s doing you little to no justice and your hard earned money can still be at RISK.
So please understand just because it’s “set up” doesn’t mean it’s SET UP PROPERLY! Ask yourself 🧐 Where is my money going? Where is it coming from? How much of it is being invested & saved? How much of it is protected? How much is at risk if things don’t go as planned? If I were to pull out some money, what would be the best option to pull from? How much is being taxed if I need to pull out for an emergency or to invest? That’s what we mean by WEALTHY INTENTION—BE INTENTIONAL WITH YOUR FINANCES.
Your circumstances and goals can change over time, so the purpose of the review IS NOT necessarily to replace what you already have. It’s an opportunity to better understand what you already have, Identify any potential missing gaps & questions, but also MAXIMIZE any benefits while reducing any RISK. Because 💳 WHEN YOU HAVE CREDIT, YOU HAVE OPTIONS.
We appreciate you being a part of Wealthy Intention LLC! 💛
Your credit transformation journey begins with a strategic consultation. Book your personalized session to discuss your current credit situation, explore your goals, and map the precise path to achieve exceptional results.
Whether your focus is repairing your credit, removing negative items, or building a stronger financial foundation, our tailored approach delivers solutions calibrated specifically to your unique circumstances.
The consultation fee is $63 which covers:
Click the button below to pay your consultation fee and take the first decisive step toward financial freedom!
$63
One-time consultation fee to begin your credit repair journey
IMPORTANT:
After you make the payment it will automatically redirect you to my booking link. PLEASE READ THE DESCRIPTION IN THE BOOKING LINK AND DO THAT PART FIRST‼️
Once that part is completed you can then finish filling out the questionnaire to book your appointment.
Please choose the best time where you will have the LEAST AMOUNT OF DISTRACTIONS.
Talk to you soon! 🙌